Seven days, two blocs moving in parallel. On the American side, SpaceX, OpenAI and Anthropic line up their S-1 filings within a six-month window, while Anthropic aims for its first operationally profitable quarter and a California jury sends Elon Musk to the ropes. On the European side, eight French tech champions unveil the AION consortium to carry a ten-billion-euro bid, while Emmanuel Macron releases 1.55 billion for quantum and semiconductors. In the background, Cerebras has landed its IPO at a $95 billion valuation, Andrej Karpathy leaves what remained of his OpenAI ties for Anthropic, Klarna, Netflix and Figma embed agents directly in their products, and Chinese models capture 61% of OpenRouter's tokens. The week AI entered the listed markets while Europe industrialised its response.
Photos: Wikimedia Commons. SpaceX filed its public S-1 on 20 May, OpenAI a confidential S-1 around 22 May, Anthropic is aiming for October.
In this issue
- SpaceX, OpenAI, Anthropic line up their S-1s within six months
- Anthropic aims for its first operationally profitable quarter
- Cerebras +68% on its Nasdaq debut — the precedent that opens the window
- France launches AION — a European response worth ten billion euros
- Macron releases €1.55bn for quantum and semiconductors
- Karpathy joins Anthropic — phase 3 of the talent war
- Klarna, Netflix, Figma: agents enter consumer apps
- NVIDIA ships the Vera CPU — agentic compute is worth $200bn
- Chinese models: 61% of OpenRouter, 10 to 20× cheaper
- White House EO postponed, Stainless swallowed: the obstacles fall
- Key takeaways
- FAQ
1. SpaceX, OpenAI, Anthropic line up their S-1s within six months
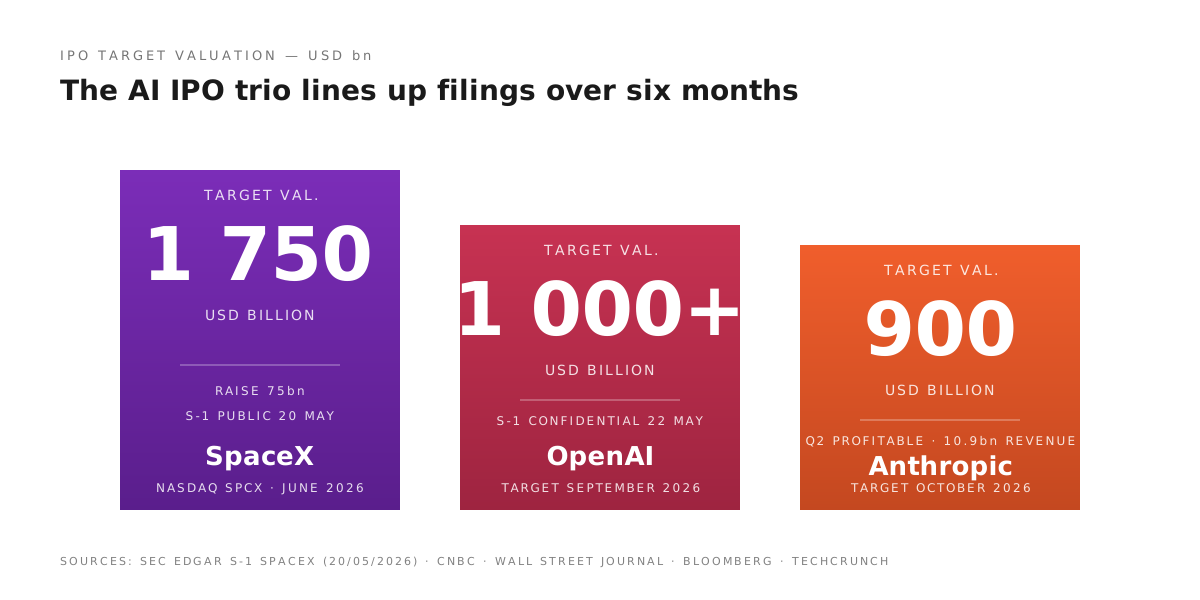
On 20 May 2026, SpaceX filed a public S-1 with the SEC, planned ticker SPCX, target valuation $1,750 billion, targeted amount raised $75 billion (SEC EDGAR — SpaceX S-1, TechCrunch, 20 May 2026). The document reveals official figures for the first time: $18.67 billion of revenue in 2025, $2.59 billion of operating losses, and in the first quarter of 2026 $4.69 billion of revenue for $1.94 billion of losses. The institutional roadshow is planned for the week of 8 June.
Two days later, OpenAI files a confidential S-1 with the SEC, with Goldman Sachs and Morgan Stanley as bookrunners (CNBC, 20 May 2026). Listing target: September 2026, sought valuation above $1,000 billion. The last private mark dated from March 2026: $852 billion after a $122 billion funding round, the largest ever carried out in venture.
Anthropic, for its part, is aiming for October 2026. The timetable is made credible by the Q2 figures (see section 2) and the discussed valuation of $900 billion (Bloomberg, 12 May 2026).
Sources: SEC EDGAR (SpaceX S-1), CNBC, Bloomberg, TechCrunch, Wall Street Journal.
The SpaceX S-1 also made official a figure that had been circulating since 13 May from a secondary source: Anthropic pays SpaceX $1.25 billion a month to rent compute capacity at the Colossus 1 datacentre until May 2029, or roughly $45 billion over the life of the contract. The AI/xAI segment integrated into SpaceX posts $818 million of revenue and $2.47 billion of operating losses in Q1 2026. The compute layer is no longer latent infrastructure: it appears in the most closely watched listing prospectus of the year.
For operators. Three immediate consequences. First, the illiquidity of AI holdings will disappear in stages: the LPs who held the labs privately will be able to trade their lines from the summer. Second, the S-1s force an unprecedented transparency on compute contracts, margins and customer concentration. Any startup that depends on a frontier provider will find in these documents the negotiating lever it did not have. Third, the window in which AI valuations can be set without market tests is closing. From September, the sector will be price-discovered in real time on listed exchanges.
2. Anthropic aims for its first operationally profitable quarter
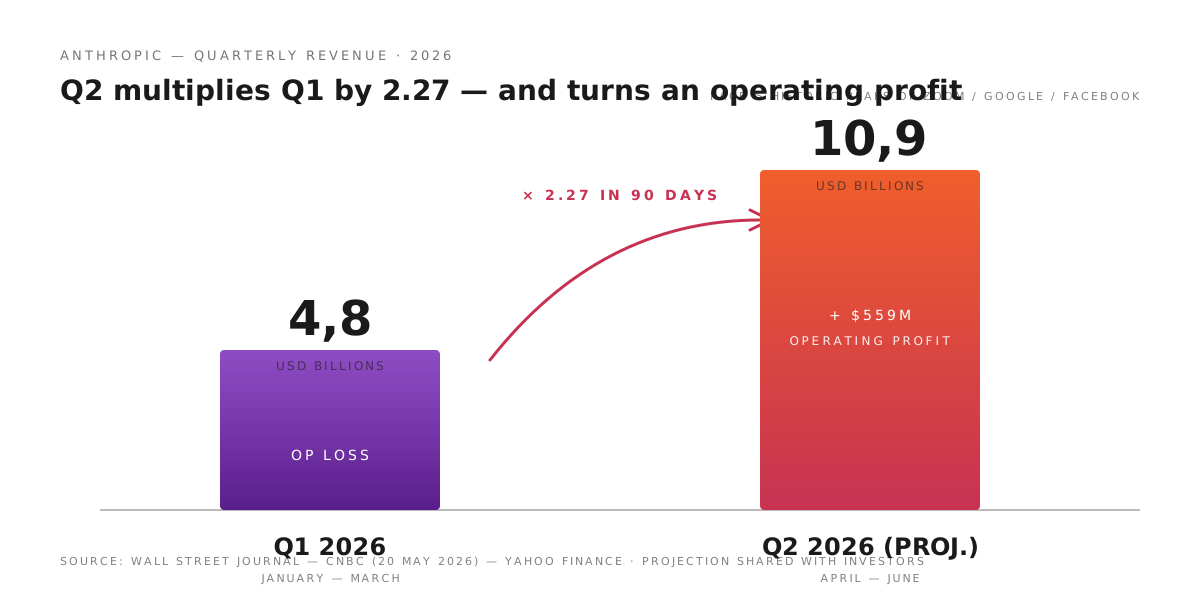
According to information given to investors and reported by the Wall Street Journal then CNBC, Anthropic forecasts for Q2 2026 revenue of $10.9 billion, more than double the $4.8 billion of Q1, and an operating profit of $559 million. It would be the company's first operationally profitable quarter ever (CNBC, 20 May 2026, Yahoo Finance).
Photo: Wikimedia Commons. Sources: Wall Street Journal, CNBC (20 May 2026), Yahoo Finance.
Sources: Wall Street Journal, CNBC (20 May 2026), Yahoo Finance, IBTimes UK.
The company warns, however, that profitability may not hold across the whole year, because of scheduled increases in compute capex. Last summer, Anthropic was telling its investors that annual profitability was not expected before 2028. The timetable has compressed by two years.
3. Cerebras +68% on its Nasdaq debut — the precedent that opens the window
On 14 May, Cerebras Systems made its Nasdaq debut after a placement of 30 million shares at $185. The stock closed its first session at $311.07 (+68%), valuing the AI chip maker at around $95 billion and raising $5.55 billion — one of the largest American tech IPOs in years (CNBC, 14 May 2026).
The figures given in the prospectus: 2025 revenue of $510 million (+76%), net profit of $88 million, against a loss of $481.6 million a year earlier. The cloud contract with OpenAI, signed in January, represents more than $20 billion over its life to 2028.

First high-volume AI IPO to succeed in 2026 — $95bn valuation after the first session.
The Cerebras IPO arrived exactly as SpaceX and OpenAI were finalising their prospectuses. It was the market test that validated three things: that AI assets can absorb valuations in the tens of billions, that institutional demand remains willing to pay an AI premium, and that historic losses are not an obstacle if the revenue trajectory is clear. Without this immediate precedent, the SpaceX/OpenAI/Anthropic trio would probably have pushed back its filings by a quarter.
For operators. Unprofitable AI startups preparing a round in 2026 now have a listed comparable on the market: Cerebras trades on revenue multiples published daily. These will become the implicit reference for term sheets from the second half.
4. France launches AION — a European response worth ten billion euros
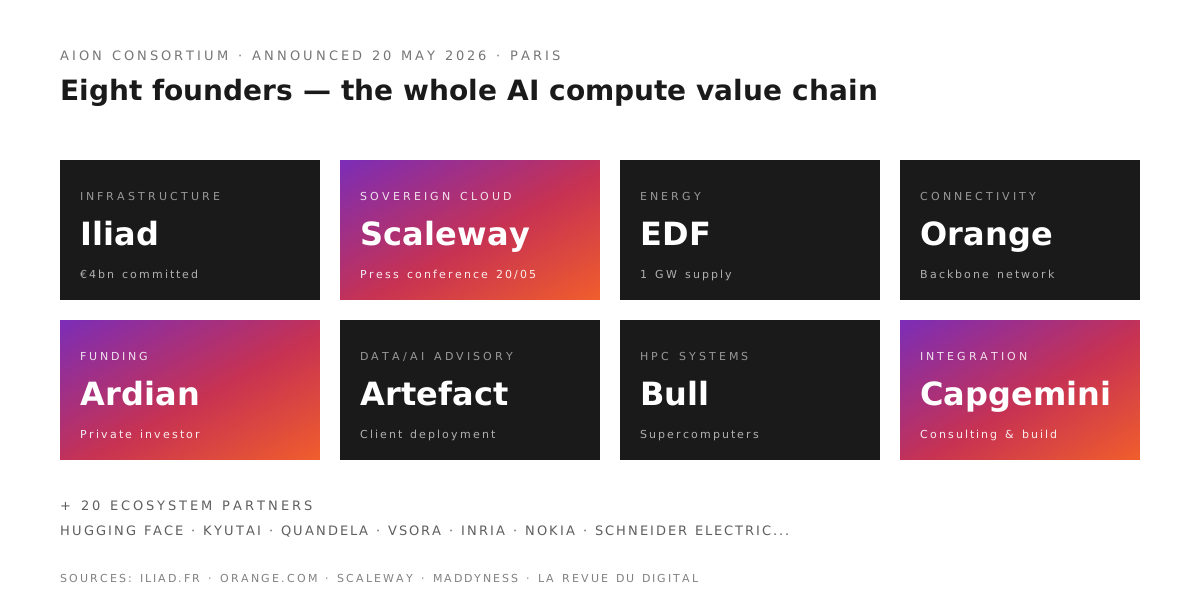
On 20 May in Paris, at Scaleway's offices near the Élysée, eight French champions unveiled the AION consortium to carry the French bid for the European InvestAI programme. The founders: Ardian, Artefact, Bull, Capgemini, EDF, Iliad, Orange, Scaleway. The alliance federates 28 companies in all, including Hugging Face, Kyutai, Quandela, VSora, INRIA, Nokia, Schneider Electric (iliad.fr press release, 20 May 2026, Maddyness, 20 May 2026).
The committed figures: a project budget of around €10 billion, a target final capacity of 1 gigawatt (first phase 100 MW), roughly 288,000 H100-equivalent GPUs, multiple sites in France not yet publicly disclosed. Iliad alone commits €4 billion. Mistral AI is in discussions to join the alliance but is not yet a member.
Source: iliad.fr, official press release 20 May 2026.


Logos: Wikimedia Commons (Iliad, Orange, EDF).
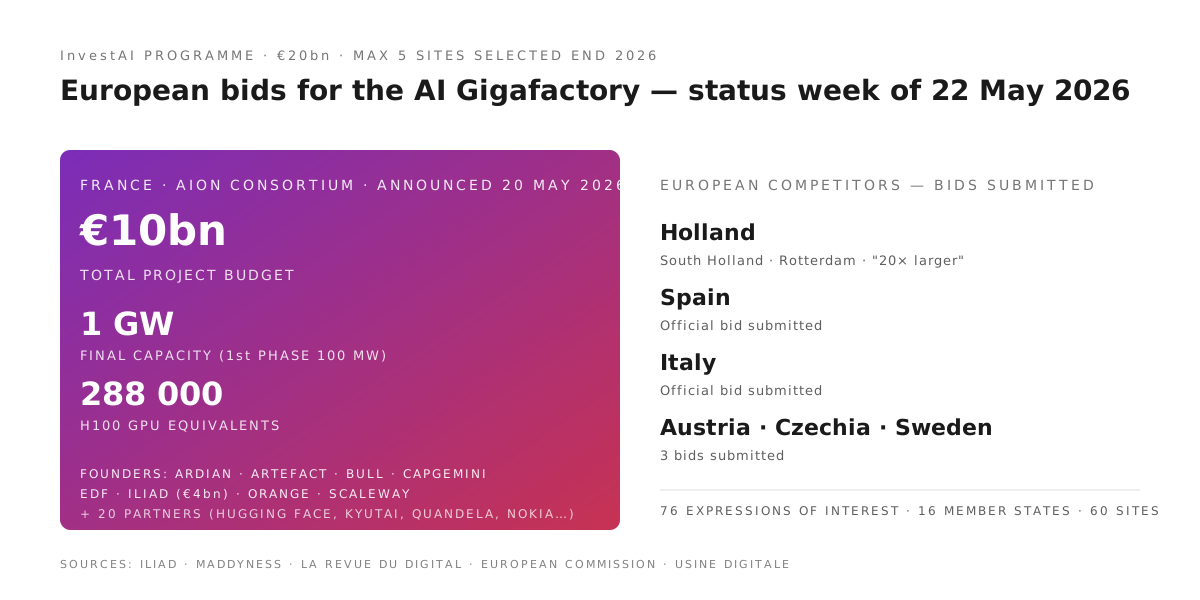
Sources: Iliad, Maddyness, La Revue du Digital, European Commission, Team France Export.
Two statements frame the founders' stance.
Thomas Reynaud (Iliad): “We don't want subsidies, we want public procurement.” The nuance is strategic. The consortium positions itself as an industrial player building usable infrastructure, not as a subsidy file to be wrung out of Bercy or Brussels.
Damien Lucas (Scaleway): “Today, 80% of the world's computing power is on American territory.” The observation sizes up the stakes: the French response aims to repatriate a share of critical compute into European jurisdiction.
The European InvestAI programme mobilises €20 billion to select at most five AI Gigafactory sites by the end of 2026 (European Commission — AI Factories). The European Investment Bank (EIB) co-finances up to 17% of capex. The Commission received 76 expressions of interest covering 60 sites in 16 member states. France is in direct competition with the Netherlands (a project near Rotterdam described as “20 times larger than current plants”), Spain, Italy, Austria, the Czech Republic and Sweden. Construction will start in 2027, the pilot operation in 2027 and full scale in 2028.
For operators. AION is the first large-scale AI compute infrastructure whose ownership stays in European jurisdiction. For any company whose AI use is under a sovereignty constraint (health, defence, banking, public sector), the effective availability of this capacity in 2028 will change the grid of conceivable providers. The first anchor contracts will probably be negotiated from 2026, in parallel with site selection.
5. Macron releases €1.55 billion for quantum and semiconductors
On the same 22 May, Emmanuel Macron visited the CEA's Très Grand Centre de Calcul (TGCC) at Bruyères-le-Châtel. The president announced a total of €1.55 billion in additional funds released for two strategic sectors: €1 billion for quantum and €550 million of French commitment to the European IPCEI Advanced Semiconductor Technologies programme (France 24, 22 May 2026, CNEWS).
Photo: Wikimedia Commons (Emmanuel Macron, 2024). Sources: France 24, CNEWS, Maddyness.
The quantum envelope is used to accelerate the Proqcima public procurement programme over 2026-2032, to co-finance European supercomputers, to support research and talent and to invest in quantum sensors and communications. The official quote: “France must stay in the race.”
The sequence is no accident. AION on 20 May in Paris; Macron on 22 May at the CEA. In under 72 hours France puts down both legs of its industrial response: computing capacity (AION) and the next-generation computing building blocks (quantum and semiconductors).
Two signals from the same week add to this. Hugging Face — a Franco-American company, and one of AION's 28 partners — closed a $200 million Series D led by Salesforce Ventures, at a $4 billion valuation (double that of the Series C) (AIBase, May 2026). Mistral AI acquired the young Austrian company Emmi AI on 19 May, which specialises in industrial simulation models (aerodynamics, crash), with some thirty engineers joining Mistral during 2026 (WinBuzzer, 20 May 2026). Mistral is also signing a set of partnerships in Singapore (HTX, Singtel, NCS, ST Engineering) that extends its ASEAN presence.
6. Karpathy joins Anthropic — phase 3 of the talent war
On 19 May, Andrej Karpathy announced on X that he is joining Anthropic (CNBC, 19 May 2026). Karpathy is one of the eleven founding members of OpenAI and the former head of AI at Tesla. He will lead a new team working on using Claude to accelerate pre-training research, under Nick Joseph (Head of Pretraining).
Photo: Wikimedia Commons (Andrej Karpathy, OpenAI). Sources: CNBC, TechCrunch, Axios (19 May 2026).
Three simultaneous readings.
First, Anthropic's bet: the next acceleration in model capability will not come from raw scaling, but from using current models to accelerate research itself. Karpathy is exactly the profile likely to operationalise this thesis.
Second, the employer brand. In eighteen months Anthropic has built a high-profile recruiting pattern. Six unicorn CTOs (Workday, Instagram, Box among them) left their posts to join Anthropic as individual contributors (TheStreet). Ross Nordeen, a founding member of xAI and ex-Tesla, made the same move on the very day the Colossus deal was announced. The Anthropic brand now attracts the rarest profiles against Meta, which has nonetheless documented signing bonuses of $100 million per senior engineer poached from OpenAI (a figure confirmed by Altman on the Uncapped podcast).
Finally, the AI talent war has entered a characteristic phase 3. Phase 1 (2023-2024): recruiting the rare ML researchers. Phase 2 (2025): rebuilding the enterprise commercial machine by poaching GTM executives from legacy SaaS. Phase 3 (2026): re-internalisation of public stars. Karpathy, Mira Murati and her team gone to Meta, Schulman at Anthropic. The symmetrical figures become employees of the big labs again.
7. Klarna, Netflix, Figma: agents enter consumer apps
Three product announcements this week validate a shift of the AI agent from the development environment to end business workflows.
Klarna launched a Shopping Search app in ChatGPT on 20 May, giving access to more than 100 million products and 400 million merchant listings across 13 markets, with real-time prices (BusinessWire press release, PYMNTS). The app is powered by the Klarna Product Search MCP server. The stock gained 4% on the announcement. AI traffic to retail: +700% over the 2025 peak season, conversion 31% higher than conventional channels.
Netflix unveiled at its Upfront on 13 May — the dominant media relay this week — a suite of AI agents designed to build, optimise and buy its advertising inventory autonomously (Adweek, PPC Land). Netflix's 2026 advertising revenue is expected at $3 billion, double 2025. 250 million monthly active users.
Figma announced on 20 May the arrival of a native agent on the multiplayer canvas, fine-tuned for design workflows, with native integrations of Claude Code (Anthropic) and Codex CLI (OpenAI) directly in the Figma environment (Figma Blog, TechCrunch). Figma revenue growth: +46% YoY.


The AI agent in May 2026 is no longer a standalone product but a feature embedded in existing production apps.
For operators. The “chatbot with a drop-down menu” phase is over. Productive AI agents in 2026 embed themselves in the tools teams already use (ChatGPT, Figma, Slack, Notion, VS Code, Microsoft 365). Any internal AI initiative that requires a new dedicated interface will have to explicitly justify why it does not fit into an existing workflow. User friction has become the main source of failure in enterprise AI deployments.
8. NVIDIA ships the Vera CPU — agentic compute is worth $200bn
On 18 May, NVIDIA shipped the first units of its Vera CPU, the first processor explicitly designed for agentic workloads. First customers: Anthropic, OpenAI, SpaceX AI and Oracle Cloud (TechCrunch, 20 May 2026, Dataconomy, 21 May 2026).
Photo: Wikimedia Commons. Sources: TechCrunch, Dataconomy, NVIDIA Investor Relations.
The key figure in NVIDIA's Q2 forecast ($91 billion of revenue announced) appears in a context combining two simultaneous movements: the maturity of Rubin GA on the GPU side, and the opening of an adjacent CPU market never really served by NVIDIA until now. The $80 billion buyback acts as a cushion for the stock against the guidance.
Industrial reading: what used to set the marginal cost of an AI task was GPU reasoning. With an agent that executes tool calls, reads files, writes to databases, the marginal cost becomes CPU orchestration. NVIDIA is trying to be vertical on both layers at once. If Vera keeps its promise, the immediate competitor is not AMD or Intel on the server, it is Apple Silicon and ARM at the edge.
The Vera architecture, whose first CPU units were delivered on 18 May 2026 to Anthropic, OpenAI, SpaceX AI and Oracle Cloud.
9. Chinese models: 61% of OpenRouter, 10 to 20× cheaper
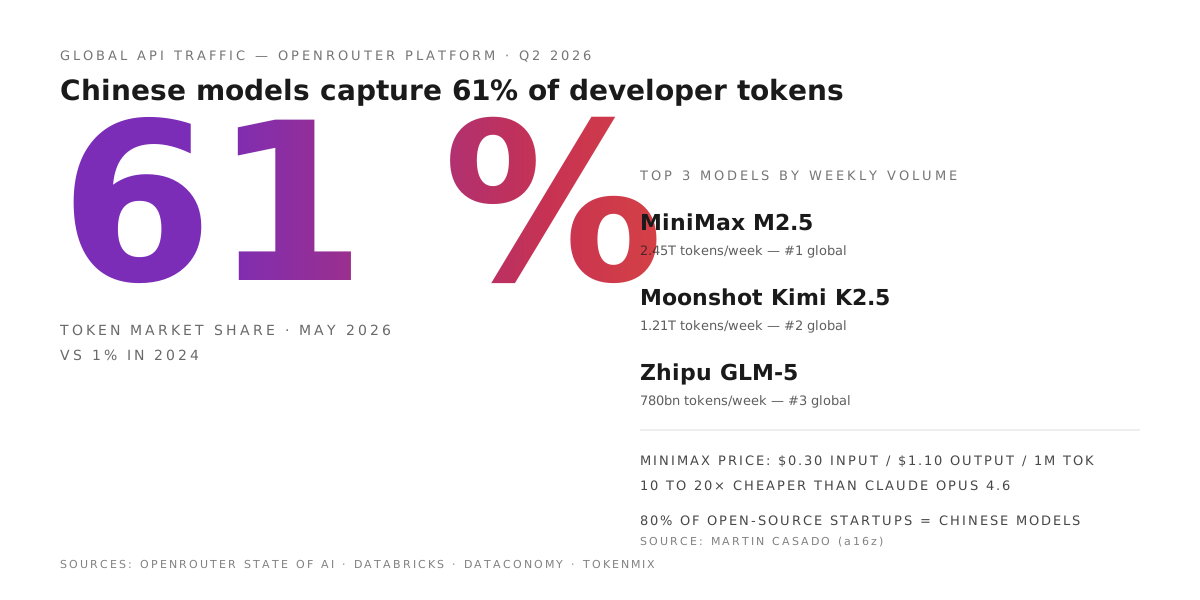
OpenRouter, the API routing platform most used by independent developers, now measures a dominant share of Chinese models in overall traffic. The figures: 61% market share in tokens, against 1% in 2024. The global top 3 is made up of MiniMax M2.5 (2.45 trillion weekly tokens), Moonshot Kimi K2.5 (1.21T) and Zhipu GLM-5 (780bn). DeepSeek V3.2 takes fifth place (Dataconomy, OpenRouter State of AI).
Sources: OpenRouter, Dataconomy, Databricks, TokenMix.
The main driver is the price gap. MiniMax M2.5 charges $0.30 per million input tokens and $1.10 output, against $15 input and $75 output for Claude Opus 4.6: a raw ratio of 10 to 20 times. According to Martin Casado (a16z), 80% of startups deploying an open-source stack run Chinese models.
On benchmarks, Kimi K2.6 (released 20 April 2026) became the first open-weights model to beat GPT-5.4 high on SWE-Bench Pro (58.6 vs 57.7), also ahead of Claude Opus 4.6 max (53.4). Qwen 3.6 Plus (Alibaba) ships a one-million-token context. Zhipu GLM-5 doubled its parameter count and adopted DeepSeek Sparse Attention.
One detail circulated this week via an internal Anthropic document: the technical lead of American labs over Chinese models is estimated at “a few months”, no longer one or two years as it was presented in 2024.
10. White House EO postponed, Stainless swallowed: the obstacles fall
Three background movements whose cumulative effect structures the week.
Musk vs OpenAI verdict (19 May). A nine-member California jury unanimously rejected, in under two hours, all of Elon Musk's claims against Sam Altman, Greg Brockman and OpenAI. Judge Yvonne Gonzalez Rogers closed the case on statute-of-limitations grounds (NPR, Al Jazeera). Musk announced an appeal before the Ninth Circuit. The immediate dismissal frees OpenAI from structural uncertainty just before the S-1 filing.
White House AI Executive Order postponed (21 May). The voluntary 90-day review framework for frontier models, which was to include a classified evaluation by the NSA, was postponed indefinitely. Origin of the delay: an internal disagreement between the pro-innovation factions (who wanted a genuinely voluntary framework) and national security (who wanted real enforcement). Combined with the EU AI Act omnibus of 7 May, which pushed high-risk obligations back to the end of 2027, a markedly more permissive regulatory climate is setting in simultaneously on both sides of the Atlantic.
Stainless acquired by Anthropic (18 May). Anthropic acquired Stainless, the automatic SDK generation platform used by OpenAI, Google, Cloudflare, Replicate and Runway, for a reported amount above $300 million according to The Information (not confirmed by Anthropic) (TechCrunch, 18 May 2026). All Stainless hosted products will be shut down. SDKs already generated remain the customers' property. Anthropic takes control of an infrastructure layer used by its direct competitors — a typical case of adversarial infrastructure acquisition.
Microsoft, meanwhile, took Agent 365 to GA with an Anthropic Claude connector for Microsoft Purview, giving CIOs centralised visibility over Claude Enterprise and Claude Platform conversations (Microsoft Security Blog, 21 May 2026). Agent governance is becoming institutionalised.
11. Key takeaways
Six operational conclusions for the week.
| Theme | Movement | Immediate consequence |
|---|---|---|
| IPO | SpaceX public S-1, OpenAI confidential S-1, Anthropic targets October, Cerebras +68% on debut | AI illiquidity disappears in stages. Valuations enter a zone of market discipline. |
| Profitability | Anthropic $10.9bn revenue / +$559m operating profit in Q2 | First frontier lab to leave the pure-growth narrative. Listed comparable in September/October. |
| Europe | AION €10bn, Macron €1.55bn, Hugging Face Series D $200m | Two industrial legs activated in 72h: capacity (AION) and next-gen building blocks (quantum + semi). |
| Talent | Karpathy at Anthropic, Meta $100m signing bonus | Phase 3: re-internalisation of public stars. Lock in your 95th-percentile profiles now. |
| Distribution | Klarna ChatGPT, Netflix ad agents, Figma Agent + Claude Code/Codex | The agent is an embedded feature, no longer a standalone product. Justify any dedicated interface. |
| China | 61% OpenRouter, MiniMax/Kimi/GLM 10-20× cheaper, US lead at “a few months” | Multi-model becomes a contractual requirement. Test DeepSeek/Qwen alongside the proprietary stack. |
First, the financialisation of frontier labs is now public. Compute contracts, margins, customer concentrations and shareholding structures will be readable by everyone from September. Each player's pricing power will be tested in real time.
Second, Europe has stopped communicating about sovereignty and started building. AION commits private capital, Macron public capital, Hugging Face secures its capital. For companies under a sovereignty constraint, the 2026-2028 timetable will offer real alternatives where there was until now a structural deficit.
Third, the technical centre of gravity remains American but the economics of inference are tipping towards China. Any startup deploying a consumer or developer product must build into its architecture the ability to route part of its traffic to a Chinese open-weights model. Not as a plan B: as a margin requirement from 2026.
12. FAQ
Why are SpaceX, OpenAI and Anthropic filing their S-1s in the same week?
SpaceX filed a public S-1 on 20 May 2026 (ticker SPCX, target valuation $1,750 billion). OpenAI filed a confidential S-1 around 22 May for a listing in September, with a target valuation above $1,000 billion. Anthropic is aiming for October 2026. The timetable is made possible by three converging factors: Anthropic's operating profitability in Q2, the verdict in OpenAI's favour in the Musk trial on 19 May, and Cerebras's successful IPO on 14 May, which validated the market's appetite for AI assets.
What is the AION consortium and how much is France committing?
AION is a consortium announced on 20 May 2026 in Paris, bringing together eight founders (Ardian, Artefact, Bull, Capgemini, EDF, Iliad, Orange, Scaleway) and 28 companies in total, including Hugging Face, Kyutai, Quandela, Nokia and Schneider Electric. The project is budgeted at €10 billion for a final capacity of 1 GW (first phase 100 MW, 288,000 H100-equivalent GPUs). Iliad alone commits €4 billion. The French bid is competing with those of the Netherlands, Spain, Italy, Austria, the Czech Republic and Sweden for the five sites selected by the European InvestAI programme (€20bn). Site selection is expected at the end of 2026.
Why is Anthropic's hiring of Andrej Karpathy a strategic signal?
Andrej Karpathy announced on 19 May 2026 that he is joining Anthropic. He is one of the eleven founding members of OpenAI and the former head of AI at Tesla. He will lead a new team working on using Claude to accelerate pre-training research, under Nick Joseph. The move validates two of Anthropic's bets: that AI-assisted research accelerates the models' lead, and that the Anthropic brand now attracts the rarest profiles ahead of Meta, which nonetheless offers signing bonuses of $100 million.
What does it mean that Chinese models capture 61% of OpenRouter tokens?
OpenRouter is the AI API routing platform most used by independent developers. In May 2026, Chinese open-weights models capture 61% of its token traffic. MiniMax M2.5 leads with 2.45 trillion weekly tokens, ahead of Kimi K2.5 (1.21T) and Zhipu GLM-5 (780bn). The main driver is the price gap: MiniMax M2.5 costs $0.30 input and $1.10 output per million tokens, 10 to 20 times less than Claude Opus 4.6. According to Martin Casado (a16z), 80% of startups relying on an open-source stack run Chinese models.
Which weak signals should be watched next week?
Four upcoming deadlines. WWDC 2026 (8-12 June) with the official presentation of iOS 27 and confirmation of the Apple Intelligence partnerships (Gemini, Claude). The SpaceX institutional roadshow from 8 June and the first analyst comments on the $1.75 trillion valuation. The NVIDIA Q2 results (forecast $91bn) and the first documented Vera CPU orders. The detailed publication of Anthropic's Q2 results and the name of the lead investor on the $900bn round.
This note is the second recap in a weekly series published every Friday. The next edition appears on 29 May 2026.