Anthropic is running too fast to afford its own compute. SpaceX is renting it the gigawatts it can no longer build. Behind the apparent paradox — Elon Musk supplying compute to the direct competitor of his own Grok — lies the official separation of two trades that until now shared a single name: AI. On one side the model, on the other the infrastructure. The 6 May 2026 deal on Colossus 1 is the first public demonstration of the split.
Photos: Wikimedia Commons (Royal Society, TechCrunch Disrupt 2019, TechCrunch Disrupt 2023).
1. The fact
On Wednesday 6 May 2026, on stage at the Code with Claude conference in San Francisco, Dario Amodei announced a compute partnership between Anthropic and SpaceX. The capacity concerned: the whole of the Colossus 1 data centre in Memphis, originally built by xAI to train Grok — about 220,000 NVIDIA GPUs (a mix of H100, H200, GB200) and more than 300 megawatts of power (xAI press release, Tom's Hardware, Al Jazeera).


Anthropic, intellectual property and models. SpaceX, legal owner of the infrastructure since the merger with xAI (February 2026).
Three clarifications change how the deal reads.
First, the legal owner is SpaceX, not xAI. SpaceX acquired xAI on 2 February 2026 in an all-stock merger (xAI valued at $250 billion, SpaceX at $1,000 billion, combined $1.25 trillion), before dissolving it into a "SpaceXAI" division on 7 May (TechCrunch, TeslaNorth). The Anthropic lease is signed with SpaceX. Which changes everything: this is not one AI lab financing another, it is an infrastructure operator renting its capacity to the biggest customer available.
Second, the use is inference, not training. The capacity is directed to Claude Pro, Claude Max, Team and Enterprise. Claude's training remains with Amazon and Google. Immediate effects announced: a doubling of Claude Code rate limits, removal of the reduction during "peak hours" for paying subscribers, a "considerable" increase in Opus API limits (The New Stack).
Finally, the amount. The press estimates it between $4 billion (Fortune) and $5 billion a year (Latent Space). No official figure. The contract duration is not public either.
2. The industrial shift
To understand why this deal exists, one must accept a shift little commented on in the general media: Anthropic has overtaken OpenAI in annualised revenue. In spring 2026, Anthropic's ARR reaches about $30 billion (VentureBeat, PYMNTS), against about $24 billion for OpenAI (Sacra). To gauge the momentum: Anthropic was at $87 million of ARR in January 2024. An 80-fold increase in twelve months.
This growth is paid for in compute. Anthropic's commitments to hyperscalers, cumulatively, exceed $300 billion over the decade:
- Amazon — $13 billion already paid in since 2023, up to $20 billion of additional milestones. In return, Anthropic commits to spend $100 billion on AWS over 10 years, on Trainium2 and 3 chips (CNBC, TechCrunch).
- Google — $10 billion immediately, up to $30 billion of milestones, a Google Cloud contract of about $200 billion over 5 years, up to a million dedicated TPUs (CNBC).
- SpaceX — $4 to $5 billion a year (press estimate), 300 MW immediately.
Anthropic is today the only frontier lab dependent on three compute suppliers simultaneously, including an indirect competitor (Google with Gemini) and a direct competitor (SpaceX with Grok). No other player has structured its infrastructure this way.
3. Code, the cash cow that forces the deal
To understand why Anthropic agrees to rent 100% of Colossus 1 from the highest bidder — including from a player who called the company "evil" eighteen months earlier — one must look at a data point that mainstream coverage of the deal passed over in silence. Claude Code alone represents about $2.5 billion of ARR in the first quarter of 2026, more than half of it in enterprise (Sacra). The product reached a billion dollars of ARR in six months after public launch — the fastest SaaS trajectory ever observed at Anthropic (Anthropic press release, November 2025).
The 6 May announcement carries indirect confirmation of this. The first effect communicated by the SpaceX partnership is not a demo of raw capacity. It is the doubling of Claude Code rate limits for Pro, Max, Team and Enterprise. Next comes the removal of peak hours for consumer subscribers, then the increase in Opus API limits (official Anthropic press release, 6 May 2026). The order is no accident: it reveals where fresh compute goes first.
The coding agent is not just a cash cow specific to Anthropic. In 2026 it became the generative AI segment densest in ARR per GPU consumed, across all players:
- Cursor (Anysphere) — $100M ARR in January 2025, then $500M in June, $1 billion at the end of 2025, $2 billion in February 2026. On 21 April 2026, SpaceX pre-empted the $2 billion raise at $50 billion pre-money by paying $10 billion to Anysphere for a purchase option at $60 billion exercisable after the SpaceX IPO targeted for June 2026 (CNBC, 21/04/2026).
- GitHub Copilot — 4.7 million paying subscribers in Q2 FY26 (January 2026), up 75% year on year.
- Replit — multiplied by 100 in a year, $250M of ARR reached in March 2026 (TechCrunch).
Four properties explain this profitability density. The user pays to produce, not to have fun or search, which justifies an ARPU of $40 to $200/month for individuals and $40 to $100/seat in enterprise, with seven-figure contracts. The ROI is measurable: a developer directly quantifies the time saved, and the buyer buys without debate. Token consumption is dense: an agent that opens a file, reads context, proposes a diff, waits for feedback and re-iterates burns ten times more tokens than an average chat conversation. The switching friction is high: changing dev tools means relearning shortcuts, conventions, a workflow.
Reading the SpaceX–Anthropic deal in the light of this data: Anthropic is not buying compute for cosmetic features. It is buying inference capacity to serve the line where each GPU hour converts directly into recurring enterprise revenue. Code pays for the infrastructure SpaceX has just put on the market.
 cursor.com — $60bn option (CNBC, 21/04/2026)
Photo: Fortune / Getty Images. Logo: Cursor (Anysphere) via Wikimedia Commons.
Official Cursor manifesto published three weeks after the SpaceX offer. Composer (proprietary model) trained on Colossus. Official Cursor YouTube channel.
4. The real bottleneck
Money is no longer the constraint. AI capex of the four main hyperscalers (Microsoft, Meta, Amazon, Google) will reach between $650 and $725 billion in 2026, about 75% of it devoted to AI, i.e. ~$450 billion (CreditSights via 24/7 Wall St, Introl). Microsoft alone plans $190 billion of capex in 2026.


Blackwell orders placed in 2026 = deliveries expected in 2027. The shortage is no longer financial, it is physical.
This explains the most important event in the OpenAI/Microsoft calendar in 2026. In April, OpenAI obtained the lifting of its cloud exclusivity with Microsoft, a cap on revenue share and the extension of the IP licence to 2032 (CNBC). Microsoft, valued at more than $3,000 billion, no longer supplies enough compute on its own to the historic leader. Anthropic sees it too: Fortune documented in April 2026 a perceptible degradation in Claude's performance, attributed by several users to the compute shortage (Fortune, 14 April 2026).
The AI battle in 2026 is no longer a battle of models. It is a battle of gigawatts. Models equalise quickly. Power plants do not.
5. The chessboard
Three players, three structurally different positions.
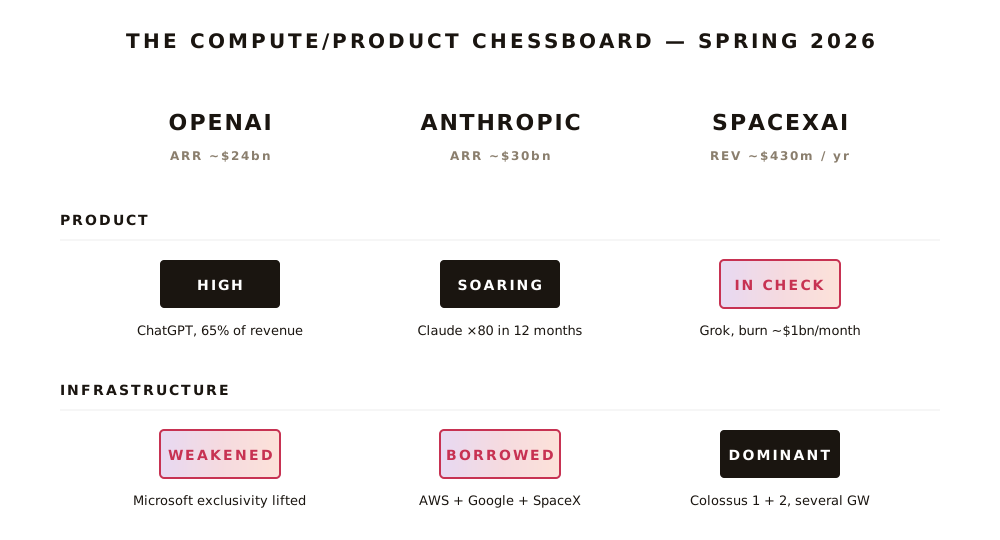
OpenAI: strong product, weakened infrastructure. Anthropic: strong product, borrowed infrastructure. SpaceXAI: failing product, dominant infrastructure.
OpenAI. The most publicly recognised product (ChatGPT, about 65% of revenue). Valuation $852 billion after the March 2026 round. Microsoft compute exclusivity lifted. It must now source compute elsewhere. Strong product, weakened infrastructure.
Anthropic. The fastest-growing product (ARR $30bn, multiplied by 80 in a year). Total compute dependence on outside hyperscalers, now including SpaceX. Strong product, infrastructure borrowed from three competitors.
SpaceXAI / Grok. Dominant infrastructure (Colossus 1 + Colossus 2, several gigawatts announced in time). Commercially failing product: Q3 2025 at $107 million of quarterly revenue for a $1.46 billion loss in the quarter alone, burn estimated at $1 billion a month (Sacra). Failing product, surplus infrastructure, shifting de facto to infra-as-a-service.
The SpaceX–Anthropic deal is the snapshot of these three positions. SpaceX monetises a capacity that Grok no longer absorbs. Anthropic fills a shortage that AWS and Google Cloud can no longer cover alone. OpenAI watches, without Microsoft to cover it entirely, a competitor obtaining what it is itself seeking.
6. The trial in the background
At the moment the deal is announced, Elon Musk is suing Sam Altman and OpenAI before the federal court in Oakland. The trial is under way, week 3. The remaining claims after several others were eliminated in May 2025: breach of charitable trust and unjust enrichment (CNBC, Wikipedia Musk v. Altman). Musk is seeking restitution of up to $150 billion to OpenAI's non-profit foundation, and the removal of Altman and Brockman from the board. Satya Nadella testified on 11 May, Sam Altman on 12 May. Closing arguments on 14 May. Decision expected the following week.
Two facts to present without over-interpreting.
Musk's grievance bears specifically on OpenAI's trajectory: non-profit status (2015), creation of a capped-profit subsidiary (2019), conversion to a Public Benefit Corporation with removal of the 100x cap (October 2025). Anthropic was never a non-profit — a PBC since 2021 with a Long-Term Benefit Trust as a mission-lock mechanism. Musk's legal grievance does not apply to Anthropic. Funding Anthropic is therefore not a contradiction of the trial against OpenAI: it is a parallel attack, on another terrain.
The calendar. Announcement of the deal on 6 May, Altman's testimony on 12 May, closing arguments on 14 May. Coincidence or calendar coup, the effect is there: the press covered the Anthropic–SpaceX deal while the jurors listened to Altman defend OpenAI's trajectory.
7. What it changes for you
For operators who integrate these models into a product or a critical workflow, four practical points.
Choosing a model now means choosing a compute exposure. Claude lives on AWS, Google Cloud and SpaceX. GPT lives on Microsoft and now other providers. Grok lives on Colossus 2. An outage or degradation on any of these layers affects the service you consume. Ask your model provider for the map of its compute sourcing, and the planned redundancy.
Model the risk of a non-technical cut-off. The "evil detector" clause announced by Elon Musk is probably not in the contract. But the precedent is publicly set: an infrastructure provider can justify a cut-off on subjective, unilateral grounds, with no arbiter. If your dependence on a model is strong, plan for the scenario "my provider's compute provider changes its mind".
Track infrastructure and model as two distinct risks. The Claude degradation documented in April 2026 was not a model problem, it was a capacity crisis. A model benchmark does not see it. SLA monitoring does not either. Put in place response-quality signals in production, not just uptime indicators.
Anticipate shortage windows. The 2026 Blackwell orders will be delivered in 2027. Pressure on inference capacity will not resolve within the next twelve months. The most consuming uses — long generation, autonomous agents, large-scale code — will be the first exposed to rationing, in the form of price rises, stricter limits or silent degradations.
The SpaceX–Anthropic deal is not an ideological reconciliation between an anti-woke Musk and a safety-first Anthropic. Nor is it a betrayal of the trial against OpenAI. It is the public confirmation that in 2026 the centre of gravity of the AI industry has shifted from the model to the infrastructure. The players who understand this shift translate it into a compute strategy. The others keep watching benchmarks.